
My Debt Gets a Fresh Start Every Six Months
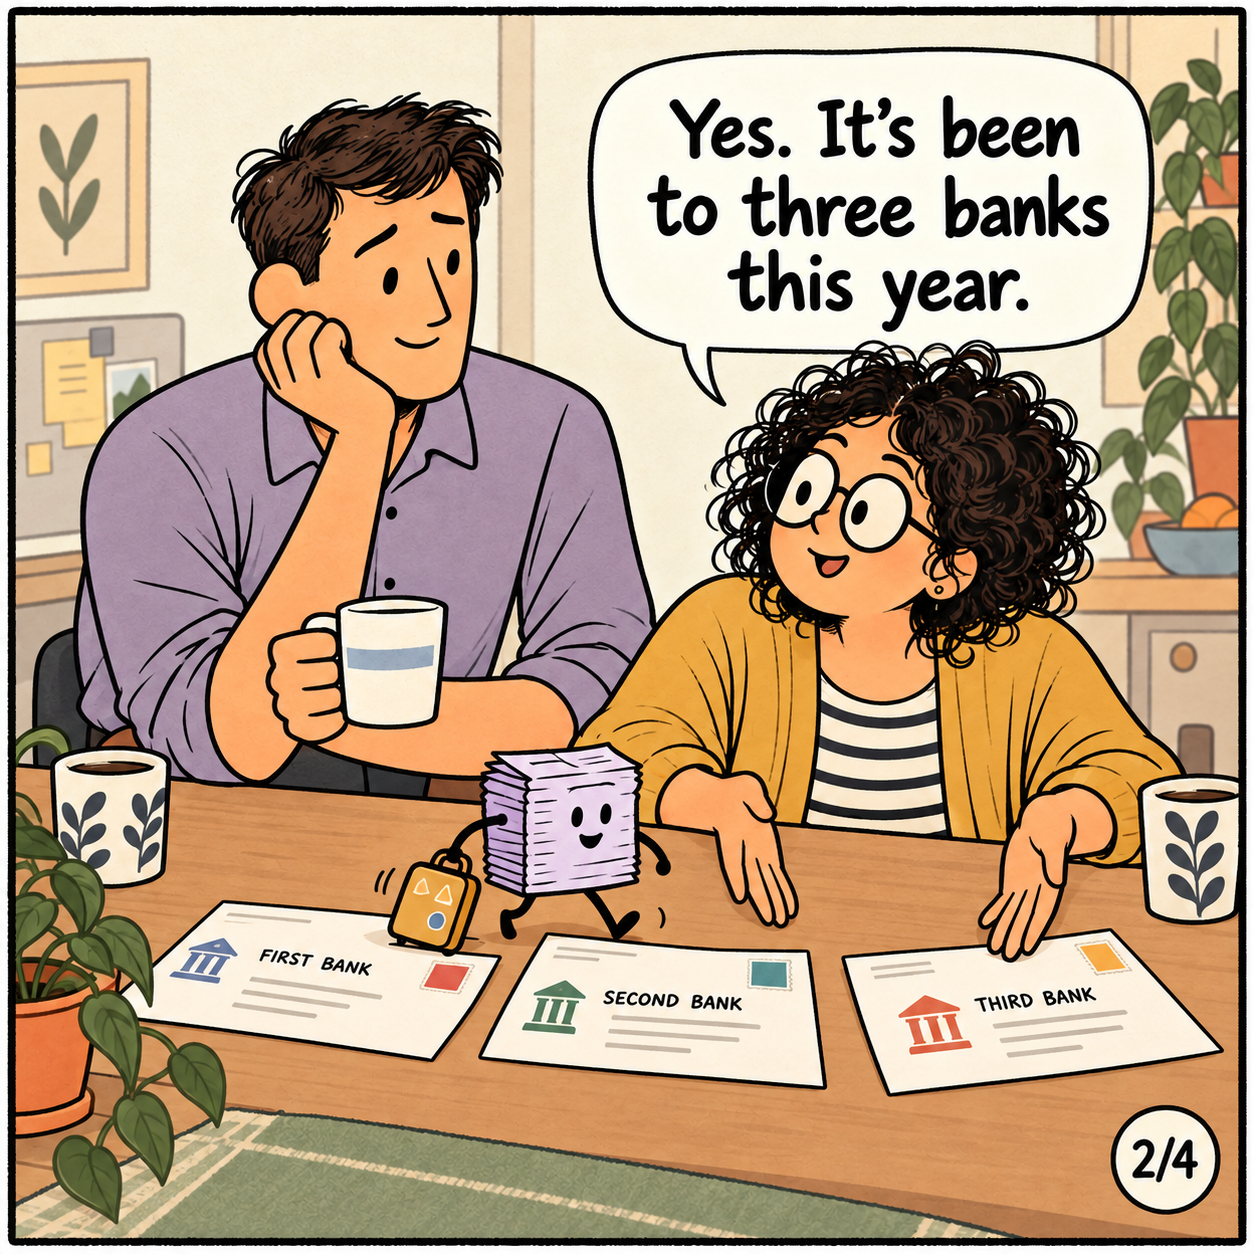
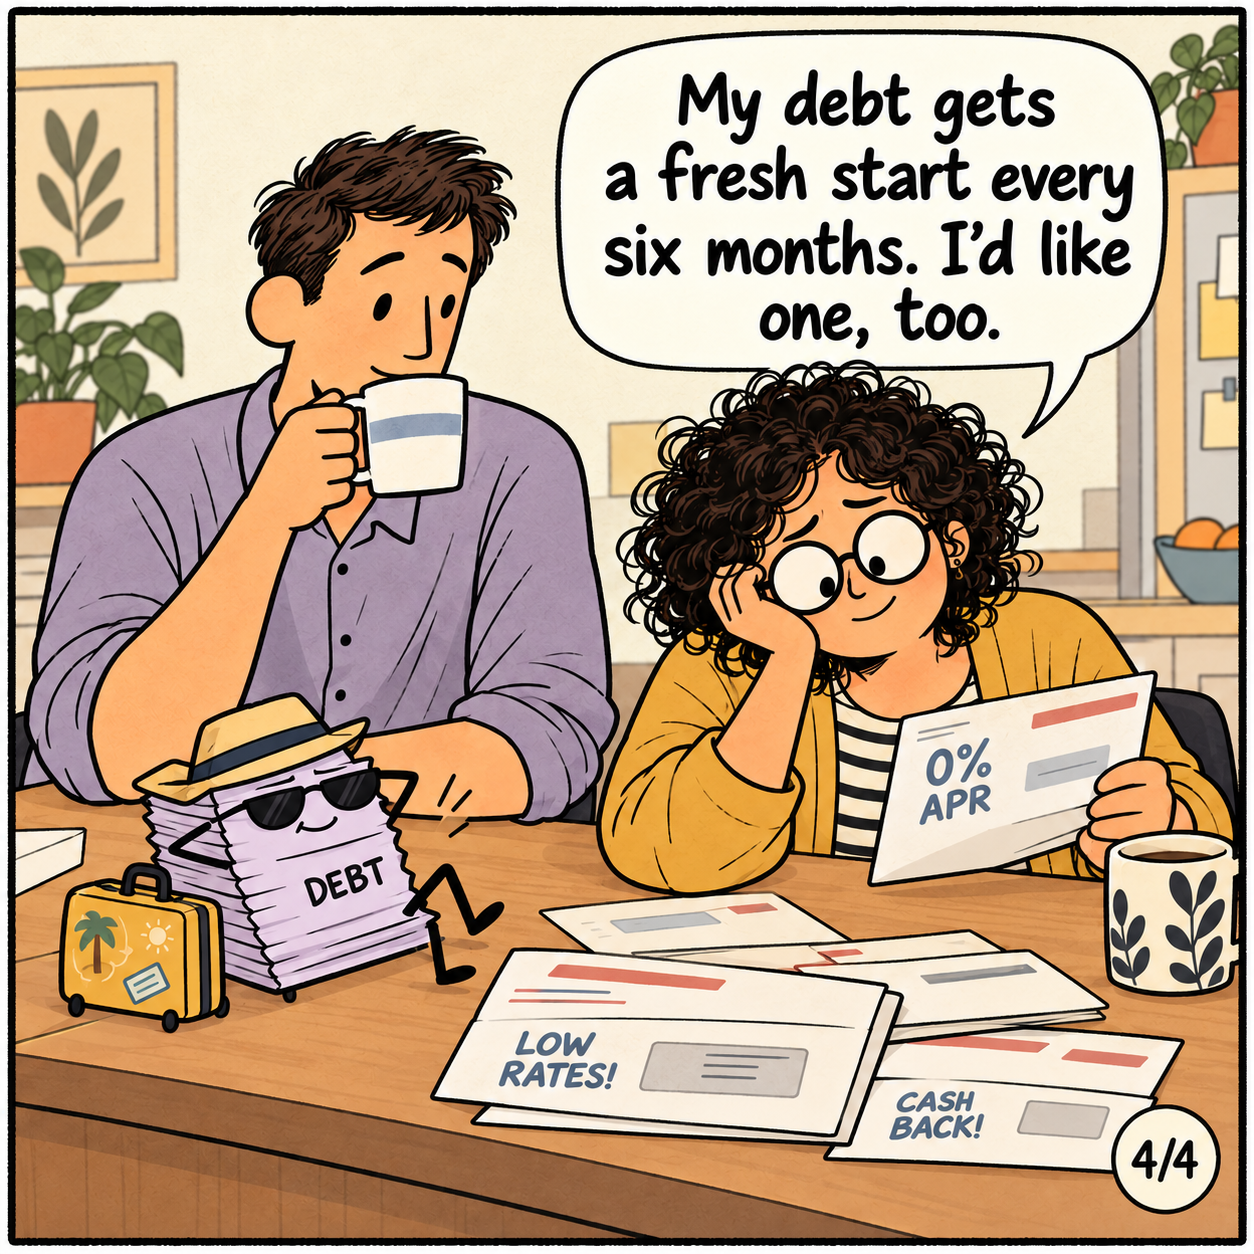
She's moved her balance to three banks this year. The debt is fine. It's been to three banks this year. She'd like a fresh start too.
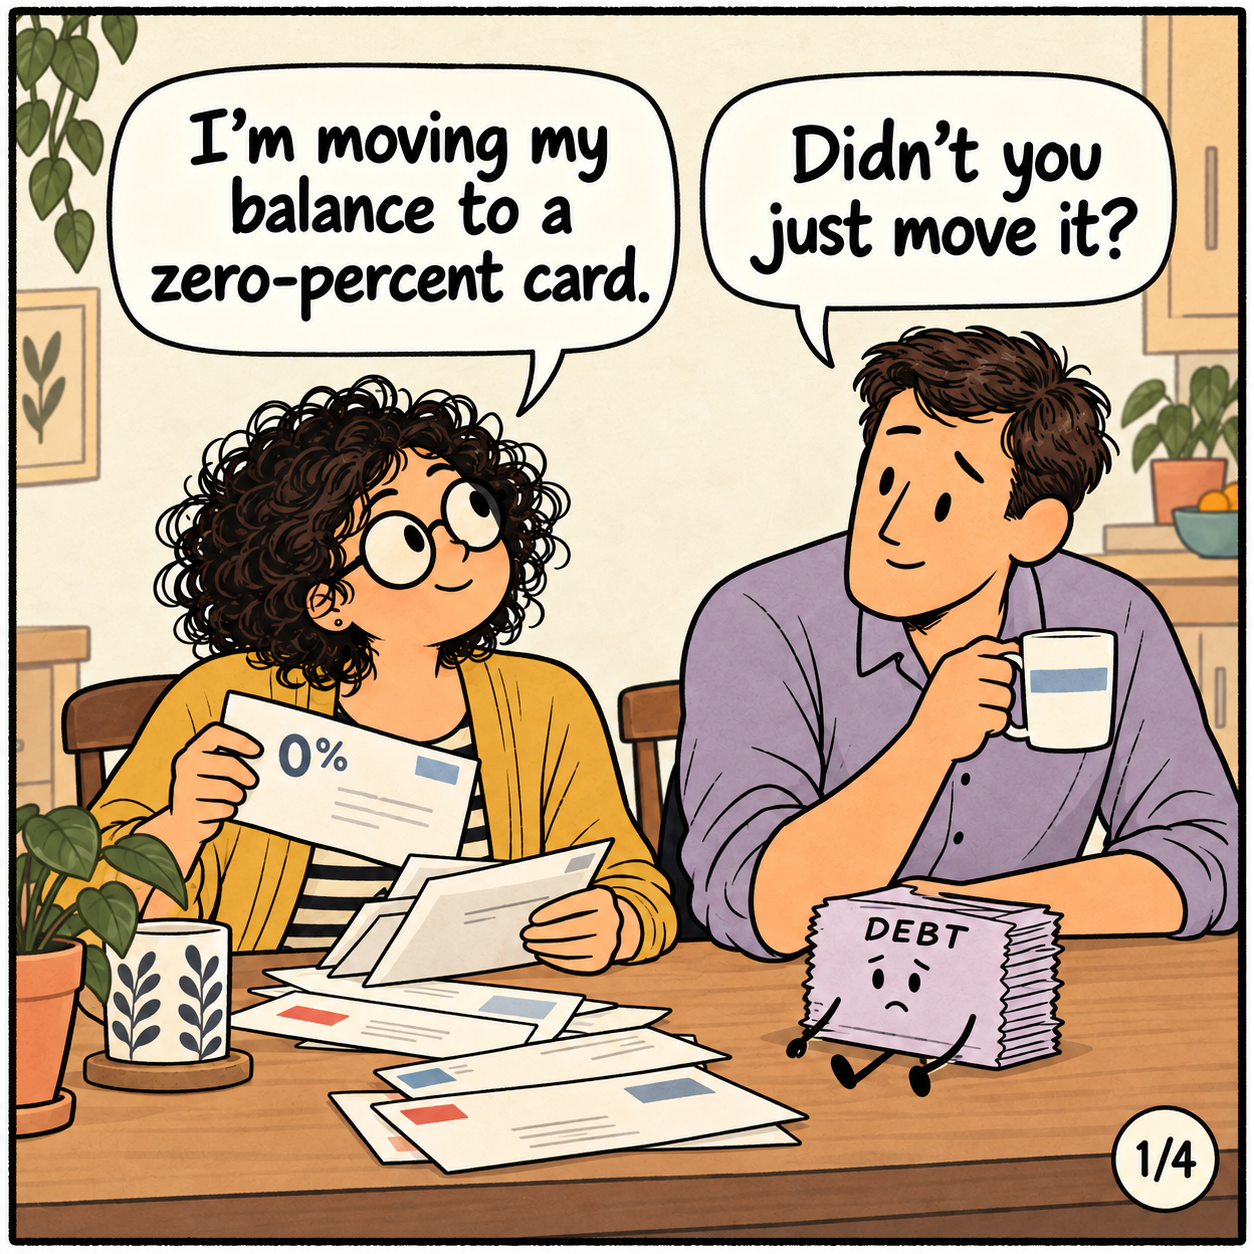
She's moving her balance to a zero-percent card.
He asks if she didn't just move it.
The debt is doing great.
It's well-traveled. It's seen First Bank, Second Bank, Third Bank. It gets a promotional period, a clean slate, a new address. Every six months or so, it packs its little suitcase and moves somewhere with better terms.
She, meanwhile, is still at the same kitchen table.
This is the part the financial advice industry doesn't quite reckon with: the system is designed to keep the debt moving, not to help you get out from under it. The zero-percent offer is real. The transfer fee is real. The rate that kicks in at month thirteen is also real. And the math only works if you pay it off before the clock runs out — which requires the kind of financial margin that people carrying this much debt often don't have.
It's not that she's bad at this. It's that she's playing a game that was designed to look like progress while staying roughly the same size.
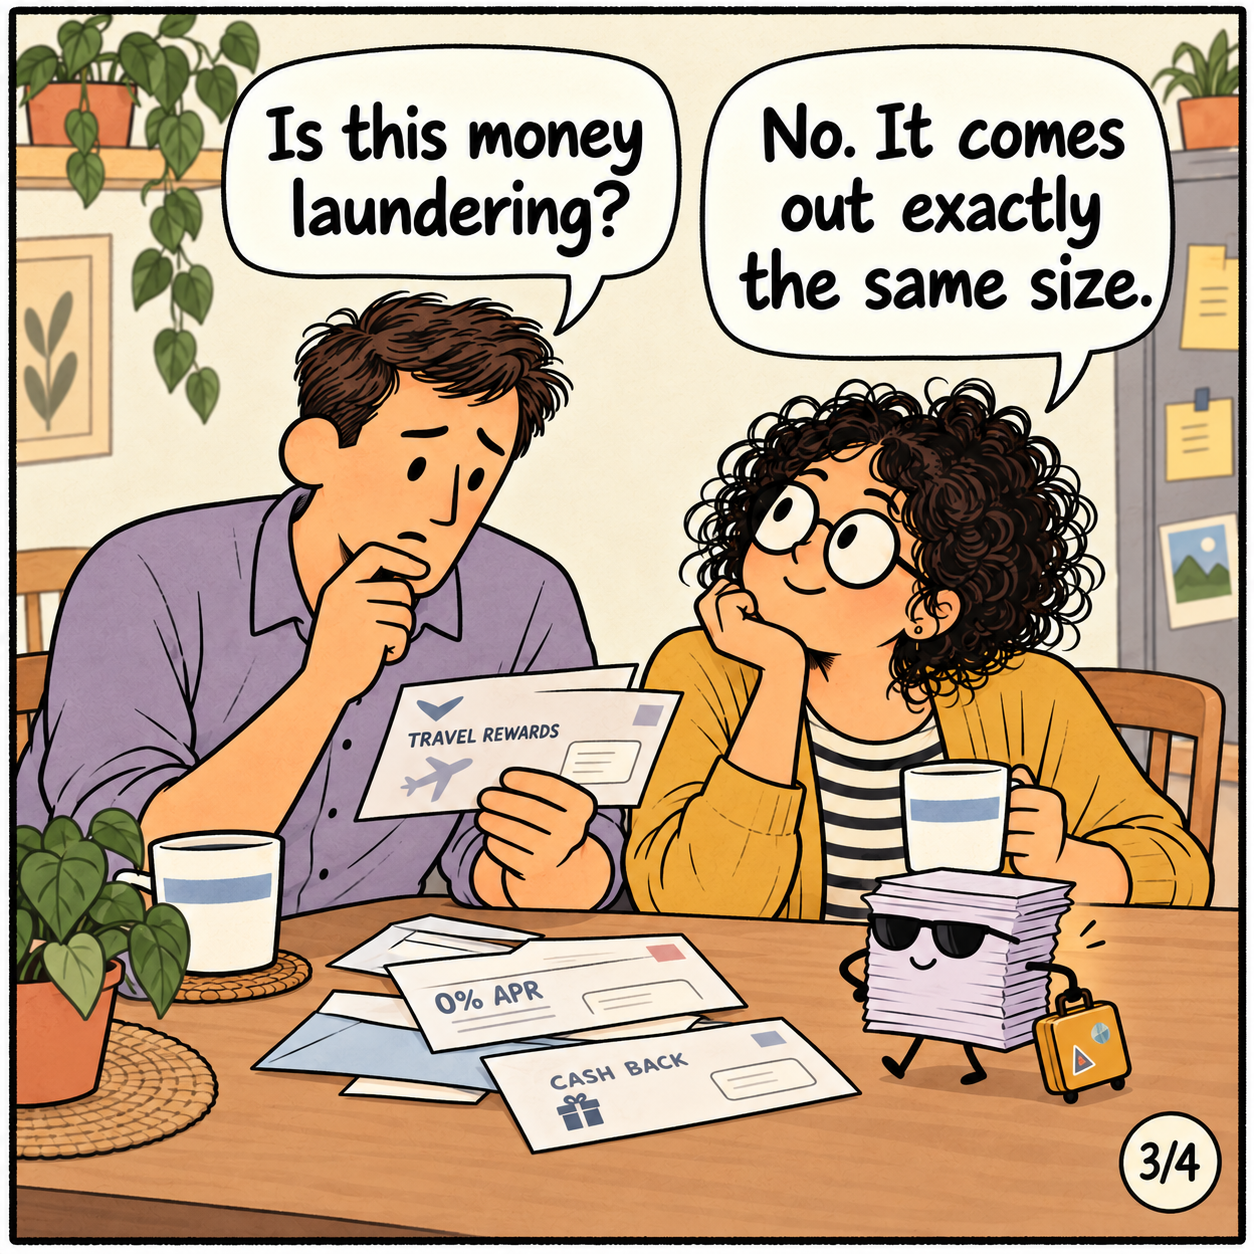
The debt comes out exactly the same size. It just has more stamps in its passport.
We the people are not bad at managing money. We are very good at managing the appearance of managing money — moving things around, optimizing the surface, keeping the plates spinning. What we're less good at is the structural question underneath: why does the fresh start always go to the debt?